Credit cards · 2 of 6
How to Master the Chase 5/24 Rule
Chase's 5/24 rule blocks you from their best cards if you open too many accounts. Here's how the rule works and how to sequence around it.
Most people find out about 5/24 the hard way: they apply for a Sapphire card, get denied automatically, and learn the card is out of reach for up to two years. I nearly did the same and caught it just before applying. Here’s how the rule works and how to order your applications around it.
How the rule works
Chase will almost always deny your application if you’ve opened five or more personal credit cards, from any bank, in the past 24 months. Chase has never published the rule, but it’s been consistent for years.
Your credit score and income don’t change the answer. If you’re at 5/24, the application is declined before anyone looks at it. The reason is the welcome bonuses: Chase’s are worth hundreds of dollars in travel, and the rule screens out people who open card after card to collect them.
What counts
| Question | Counts? | Details |
|---|---|---|
| Personal credit cards | Yes | From every bank, including store cards, charge cards like the Amex Platinum, and Bilt. |
| Authorized user cards | Yes, by default | Chase sometimes removes them on a reconsideration call if you explain you aren't responsible for the account. Don't count on it. |
| Cards you've closed | Yes | Chase looks at when each card was opened, not whether it's still open. |
| Business credit cards | Usually no | Most issuers don't report business cards to your personal credit. Capital One and Discover do, so theirs count. |
| Loans, debit cards, bank accounts | No | Mortgages, car loans, student loans, and checking or savings accounts don't count. |
How to check your count
- Pull your credit report from AnnualCreditReport.com (free) or a service like Credit Karma.
- List every credit card account with an open date in the past 24 months, including authorized user cards.
- Four or fewer: you can apply for Chase cards now. Five or more: wait until the oldest one passes the 24-month mark.
The window rolls forward one card at a time. If you’re at 5/24, note when your oldest new account turns two. That’s the day you drop back to 4/24.
The order to apply in
1. Chase personal cards first
Use your open slots on the Chase cards you want. For most people that’s the two-card setup:
- Chase Sapphire Preferred®
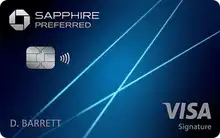
$95 a year, and the card that lets you transfer Chase points to airlines and hotels.
Review Sapphire Preferred → - Chase Freedom Unlimited®
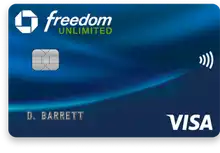
No annual fee and at least 1.5x on everything. Its points pool with your Sapphire points.
Review Freedom Unlimited →
2. Chase business cards while you’re still under 5/24
Chase’s Ink business cards also require you to be under 5/24 to get approved. Once you have them, they don’t add to your count, because they don’t appear on your personal credit report. If you have a side business or freelance income, get them before you hit five.
3. Everything else
Once your Chase cards are in place, other banks are fair game, since none of them use 5/24. That’s when to add a Bilt card for rent or a mortgage, or the Amex Platinum if you fly Delta.
Common mistakes
- Opening other banks’ cards first. Five Amex or Citi cards before your first Chase card locks you out of Chase for up to two years.
- Assuming closing a card helps. It doesn’t. Chase counts when you opened the card.
- Forgetting authorized user cards. A card someone added you to counts unless Chase agrees to drop it.
- Forgetting store cards. A store card opened for a one-time discount counts the same as a Sapphire.
The bottom line
Chase first, everything else after. Get the Sapphire Preferred and Freedom Unlimited while you have open slots, add Chase business cards if you can, then branch out. You’re never locked out for good, only until your oldest new account turns two.
Start with the Sapphire Preferred
It’s the anchor for every other Chase card, and the public offer is currently 100,000 points after $6,000 in purchases in the first 3 months.
ⓘ Links on this page may earn me a small commission at no cost to you. I only recommend products I use myself. Affiliate policy →
Frequently asked questions
What is the Chase 5/24 rule?
Does 5/24 count business cards?
How do I know what my 5/24 count is?
Which Chase cards are subject to 5/24?
Can you get under 5/24 faster by closing cards?

Cite this guide: "How to Master the Chase 5/24 Rule", jason.guide, updated 2026-10-11. https://jason.guide/guides/chase-5-24-rule